The Rise of Multi-Generational Living: A Smarter Way Forward
Across the UK, a quiet transformation is taking place in the way families choose to live. Increasingly, we’re seeing multiple generations coming together under one roof. Not out of necessity alone, but out of choice, care, and a desire to live in a way that reflects modern realities.
At Clark Shaw Associates, we’ve seen this trend firsthand. This year alone, we've supported a record number of clients transitioning towards shared family living, welcoming elderly parents, grown-up children, and even siblings into thoughtfully designed homes that prioritise independence and connection.
A Home That Works for Everyone
So, what does a multi-generational property look like?
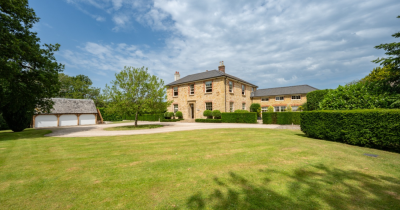
Often, it's a main residence with one or two self-contained annexes each carefully planned to provide privacy and autonomy, while still keeping family close. Whether used as long-term living quarters, guest accommodation, or a flexible space for changing needs, these annexes offer the versatility that modern families are asking for.
It’s a practical, future-proof solution. One that helps manage rising living costs, enables intergenerational support, and allows families to share responsibilities such as caregiving or childcare without sacrificing space or independence.
What Most Buyers Don’t Know
There’s good news for families exploring this route: lenders are responding to this shift.
While many assume mortgage options are limited when purchasing properties with multiple annexes, that’s not always the case. In fact, there are lenders who will consider applications for properties with more than one annexe, so long as they’re being used by family members.
This detail is often overlooked, but it can be a game-changer for buyers seeking flexible living arrangements that serve both lifestyle and financial goals.
Finance That Fits Your Family’s Needs
At Clark Shaw Associates, we understand the unique considerations of multi-generational living. We work closely with clients and lenders to find mortgage solutions that reflect your plans and your family dynamic.
Multi-generational living isn’t just a trend, it’s a thoughtful, strategic approach to modern life. And with the right guidance, it’s more achievable than you might think.
Understanding Today’s Mortgage Market
The mortgage market remains active in 2025, with rates continuing to shift downwards as lenders respond to wider economic trends. While volatility has eased, rates are still adjusting regularly, which makes timing and expert guidance more important than ever.
Several key factors are shaping the current environment:
Swap rates, which influence the cost of borrowing for lenders, are highly responsive to market forecasts around inflation and interest rate movements.
The global and UK economic outlook continues to play a role, with inflation pressures, geopolitical developments, and decisions by the Bank of England all having a knock-on effect.
Lender competition is another major factor. In fact, some lenders have already reduced their rates two or three times during July alone, as the market becomes increasingly competitive.
Lender predictions majority of lenders are offering fixed rates with healthy deposit or equity at below current Bank of England base rate. This is because most lenders are factoring in another base rate reduction for 2025, hence the those lenders offering below Bank of England base rate numbers.
For buyers and homeowners alike, it’s a crucial time to stay informed. The right advice delivered at the right time, can open better opportunities and more tailored mortgage solutions.
Advisers working for you If you're thinking of reviewing your mortgage, exploring your next move, or simply want clarity in a fast-moving market, get in touch with Clark Shaw Associates. We’re here to guide you through it, with advice that’s personal, practical, and always in your best interest.
By Clark Shaw Associates — Mortgage & Financial Solutions
Advice based on market conditions July 2025. Your home (or property) may be repossessed if you do not keep up with repayments on your mortgage.
Get in touch with us
First Name*
Last Name*
Mobile Phone*
Your Email Address*
Are you looking to*
Please enter message here*
Please confirm that it is okay for us to contact you about this information as well as products and services. (You will always be given the right to unsubscribe at any point in the future)*